
How Long Does It Take to Go From a 600 to a 700 Credit Score?
How long does it take to go from 600 to 700 credit score? Realistic timelines, a month-by-month plan, and the actions that move your score fastest.
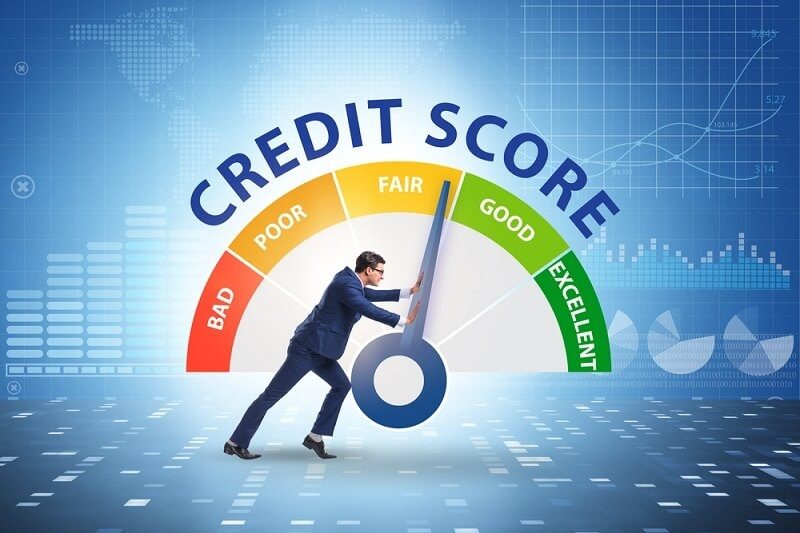
A 600 credit score puts you in "fair" territory — good enough to get some loans, bad enough to pay too much for them. A 700 score puts you in "good" territory, where the best rates start to open up. So if you're wondering how long does it take to go from 600 to 700 credit score, here's the honest answer: for most people, 6 to 18 months of consistent action. But the exact timeline depends entirely on why your score is at 600 in the first place.
This guide breaks down the realistic timelines for different situations, the actions that move your score fastest, and the mistakes that reset your clock to zero.
How Long Does It Take to Go From 600 to 700 Credit Score? The Short Answer
There is no fixed calendar for credit repair — scoring models don't work on a schedule. But patterns are clear from how millions of scores behave:
- 6 months or less: possible if your 600 is caused mainly by high credit card balances (high utilization) with no missed payments. Paying balances down can add 40–80 points fast.
- 6–12 months: typical for a score held down by one or two old late payments plus moderate balances. Steady on-time payments and lower utilization do the heavy lifting.
- 12–18+ months: realistic if collections, charge-offs, or multiple missed payments are on your report. Recent negative marks weigh heavily, and only time plus a clean streak dilutes them.
Nobody can promise you a specific date — anyone who does is selling something. But 100 points is absolutely achievable with a plan. If you haven't read it yet, start with our plain-English guide on how credit scores work so every move below makes sense.
Step 1: Find Out What's Holding Your Score at 600
Before you can fix it, you need a diagnosis. Pull your free credit reports from all three bureaus at AnnualCreditReport.com (free weekly) and look for the culprits:
- High utilization. Are your credit cards close to their limits? Balances over 30% of your limit drag scores down; balances over 80% drag them down hard.
- Late payments. Any payment 30+ days late in the last two years is likely costing you 40–80 points.
- Collections or charge-offs. Unpaid debts sent to collectors are among the heaviest anchors.
- Thin file. If you only have one or two accounts, there's little positive history to balance out the negatives.
Your situation determines your timeline. A 600 caused by maxed-out cards recovers much faster than a 600 caused by three collections.
The Actions That Move a 600 Toward 700 Fastest
Credit scores reward two things above all: paying on time (35% of your FICO score) and keeping balances low relative to limits (30%). Everything else is detail work. In order of impact:
1. Bring utilization under 30%, then under 10%
This is the fastest lever you have. Utilization has no memory in current scoring models — your score reflects this month's reported balances, not last year's. That means paying a maxed-out card down to 10% utilization can raise your score within one or two billing cycles.
Example: a $2,000 balance on a card with a $2,500 limit is 80% utilization — score poison. Pay it to $200 (8% utilization) and you could see a 40–60 point jump once the new balance is reported. If you're carrying multiple balances, our debt payoff calculator can show you your debt-free date and how extra payments speed it up.
2. Make every payment on time, starting now
One new 30-day late payment can erase months of progress. Set up autopay for at least the minimum on every account — this is the single highest-value habit in credit building. If you have old late payments, they lose sting over time: a two-year-old late payment hurts far less than a two-month-old one.
3. Don't close old cards
Closing a card with no annual fee shrinks your total available credit, which raises your utilization — the opposite of what you want. Keep old cards open with a small recurring charge (like a streaming subscription) on autopay.
4. Dispute real errors
About 1 in 5 credit reports contains an error. If you find accounts that aren't yours, wrong balances, or late payments you can prove were on time, dispute them with the bureau. Legitimate errors removed can add points quickly. Never pay a "repair" company to do this — you can dispute for free yourself.
The Month-by-Month Timeline: 600 to 700
Here's what the journey typically looks like, depending on your starting situation:
| Starting situation | Typical months to 700 | What drives the gains | |---|---|---| | 600, cards maxed out, no missed payments | 3–6 | Pay utilization under 30%, then under 10%; keep paying on time | | 600, one old late payment + moderate balances | 6–9 | Utilization drops + 6–9 months of clean payments dilute the late mark | | 600, several late payments in last 2 years | 9–15 | Long on-time streak; each clean month matters more as marks age | | 600, collections or charge-offs on report | 12–24 | Pay or settle collections, then build 12+ months of spotless history | | 600, thin file (1–2 accounts) | 6–12 | Add a second account (secured card), keep utilization low, pay on time |
A few notes on this table:
- Months 1–2 are when utilization drops show up. If you pay down a big balance today, expect to see movement after the next statement cycle reports (usually 30–45 days).
- Months 3–6 are the on-time streak building phase. This is where most people quit — the score moves slowly, and it's tempting to stop. Don't.
- Months 6+ are when old negative marks start aging into lighter territory, especially if your recent history is flawless.
Mistakes That Reset Your Clock
- Missing a payment. A fresh 30-day late can cost 60–100+ points on a 600-score file — months of work gone in one billing cycle.
- Applying for several new accounts at once. Each hard inquiry costs a few points, and multiple new accounts lower your average account age.
- Co-signing someone else's loan. Their late payments become your late payments.
- Ignoring collections. Even small collections ($50 medical bills) can anchor your score. Address them rather than hoping they vanish.
What Actually Changes When You Hit 700
The climb is worth it. At 700, you're in "good" credit territory:
- Auto loans: rates drop noticeably — often 2–4 percentage points lower than at 600.
- Mortgages: many lenders' best conventional rates start around 700+.
- Credit cards: you qualify for cards with real rewards and lower APRs instead of secured cards and fee-heavy options.
- Rentals and insurance: landlords and insurers in many states use credit-based scores, and 700 clears most bars.
On a $20,000 car loan over 5 years, the difference between a 9% rate (typical near 600) and a 6% rate (typical near 700) is roughly $1,700 in interest. That's the real prize: not the number, but what it saves you.
Your 7-Day Kickoff Plan
- Day 1–2: Pull your three credit reports and list every negative item.
- Day 3: Set autopay (minimums) on every account.
- Day 4: Make a plan to get total utilization under 30% — list balances and limits, pay the highest-utilization card first.
- Day 5: Dispute any genuine errors you found.
- Day 6: Run your numbers through the debt payoff calculator to set a payoff date.
- Day 7: Calendar a monthly 10-minute credit check-in. Consistency wins.
Going from 600 to 700 isn't magic and it isn't instant — it's a series of unglamorous, repeatable actions. Pay on time, keep balances low, give it time. Six to eighteen months from now, you'll be glad you started today.
This article is for education only and isn't financial advice.
Keep reading
How to Get Out of Credit Card Debt: A Step-by-Step Plan
Drowning in credit card debt? Follow this realistic step-by-step plan to stop the bleeding, cut interest costs, and become debt-free.
How to Build Credit From Scratch
No credit history? No problem. Learn the beginner-friendly tools and habits that build a solid credit score from zero.
How Credit Scores Work (and How to Raise Yours)
A plain-English guide to credit scores — what the number means, the five factors behind it, and practical steps to raise yours.